News from us. Ideas for you.
All in one place.
At the Helm is our weekly Monday note: one real advisor workflow, walked through start to finish. Around it live the sample interactions you can download and reuse, and news on what we are shipping. Drill into any of them below.
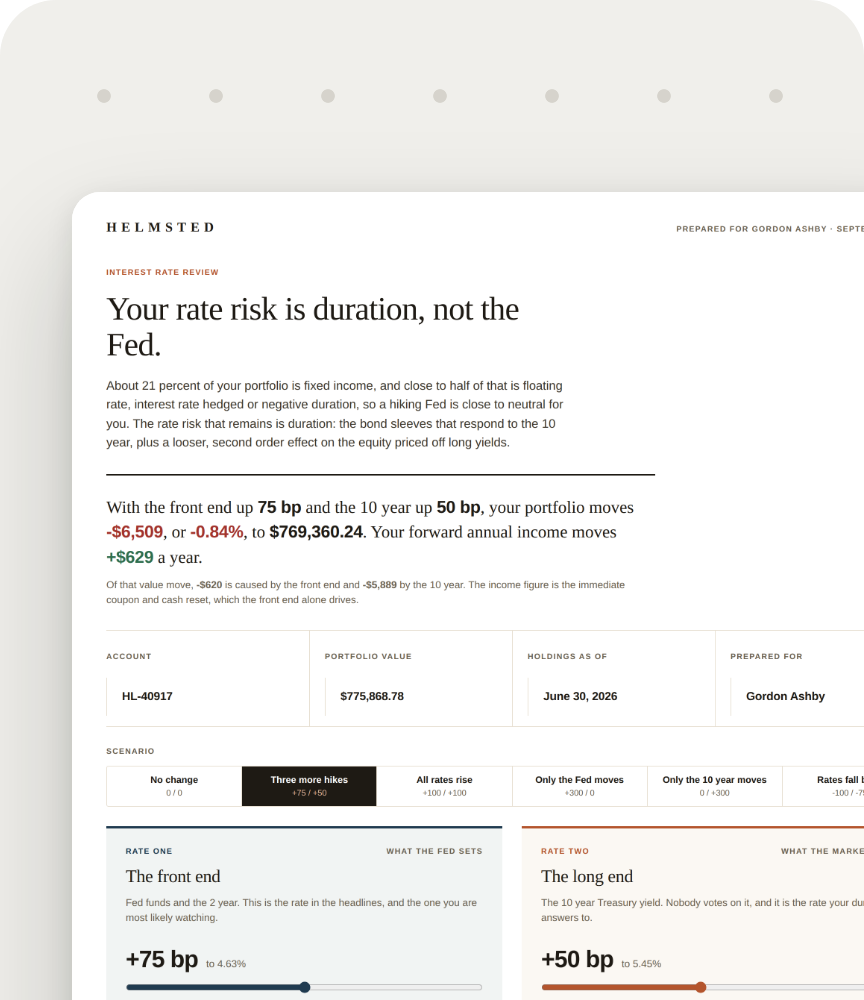
A client watched the Fed raise rates and asked what it does to his portfolio. From a dropped-in statement, Helmsted helped his advisor split every holding's rate risk between the rate the Fed sets and the rate the market sets, and show that the hikes cost him $620 in price and add $629 a year of forward income, close to a wash, while the duration in his bond sleeves answers to the 10 year.
Read it ↗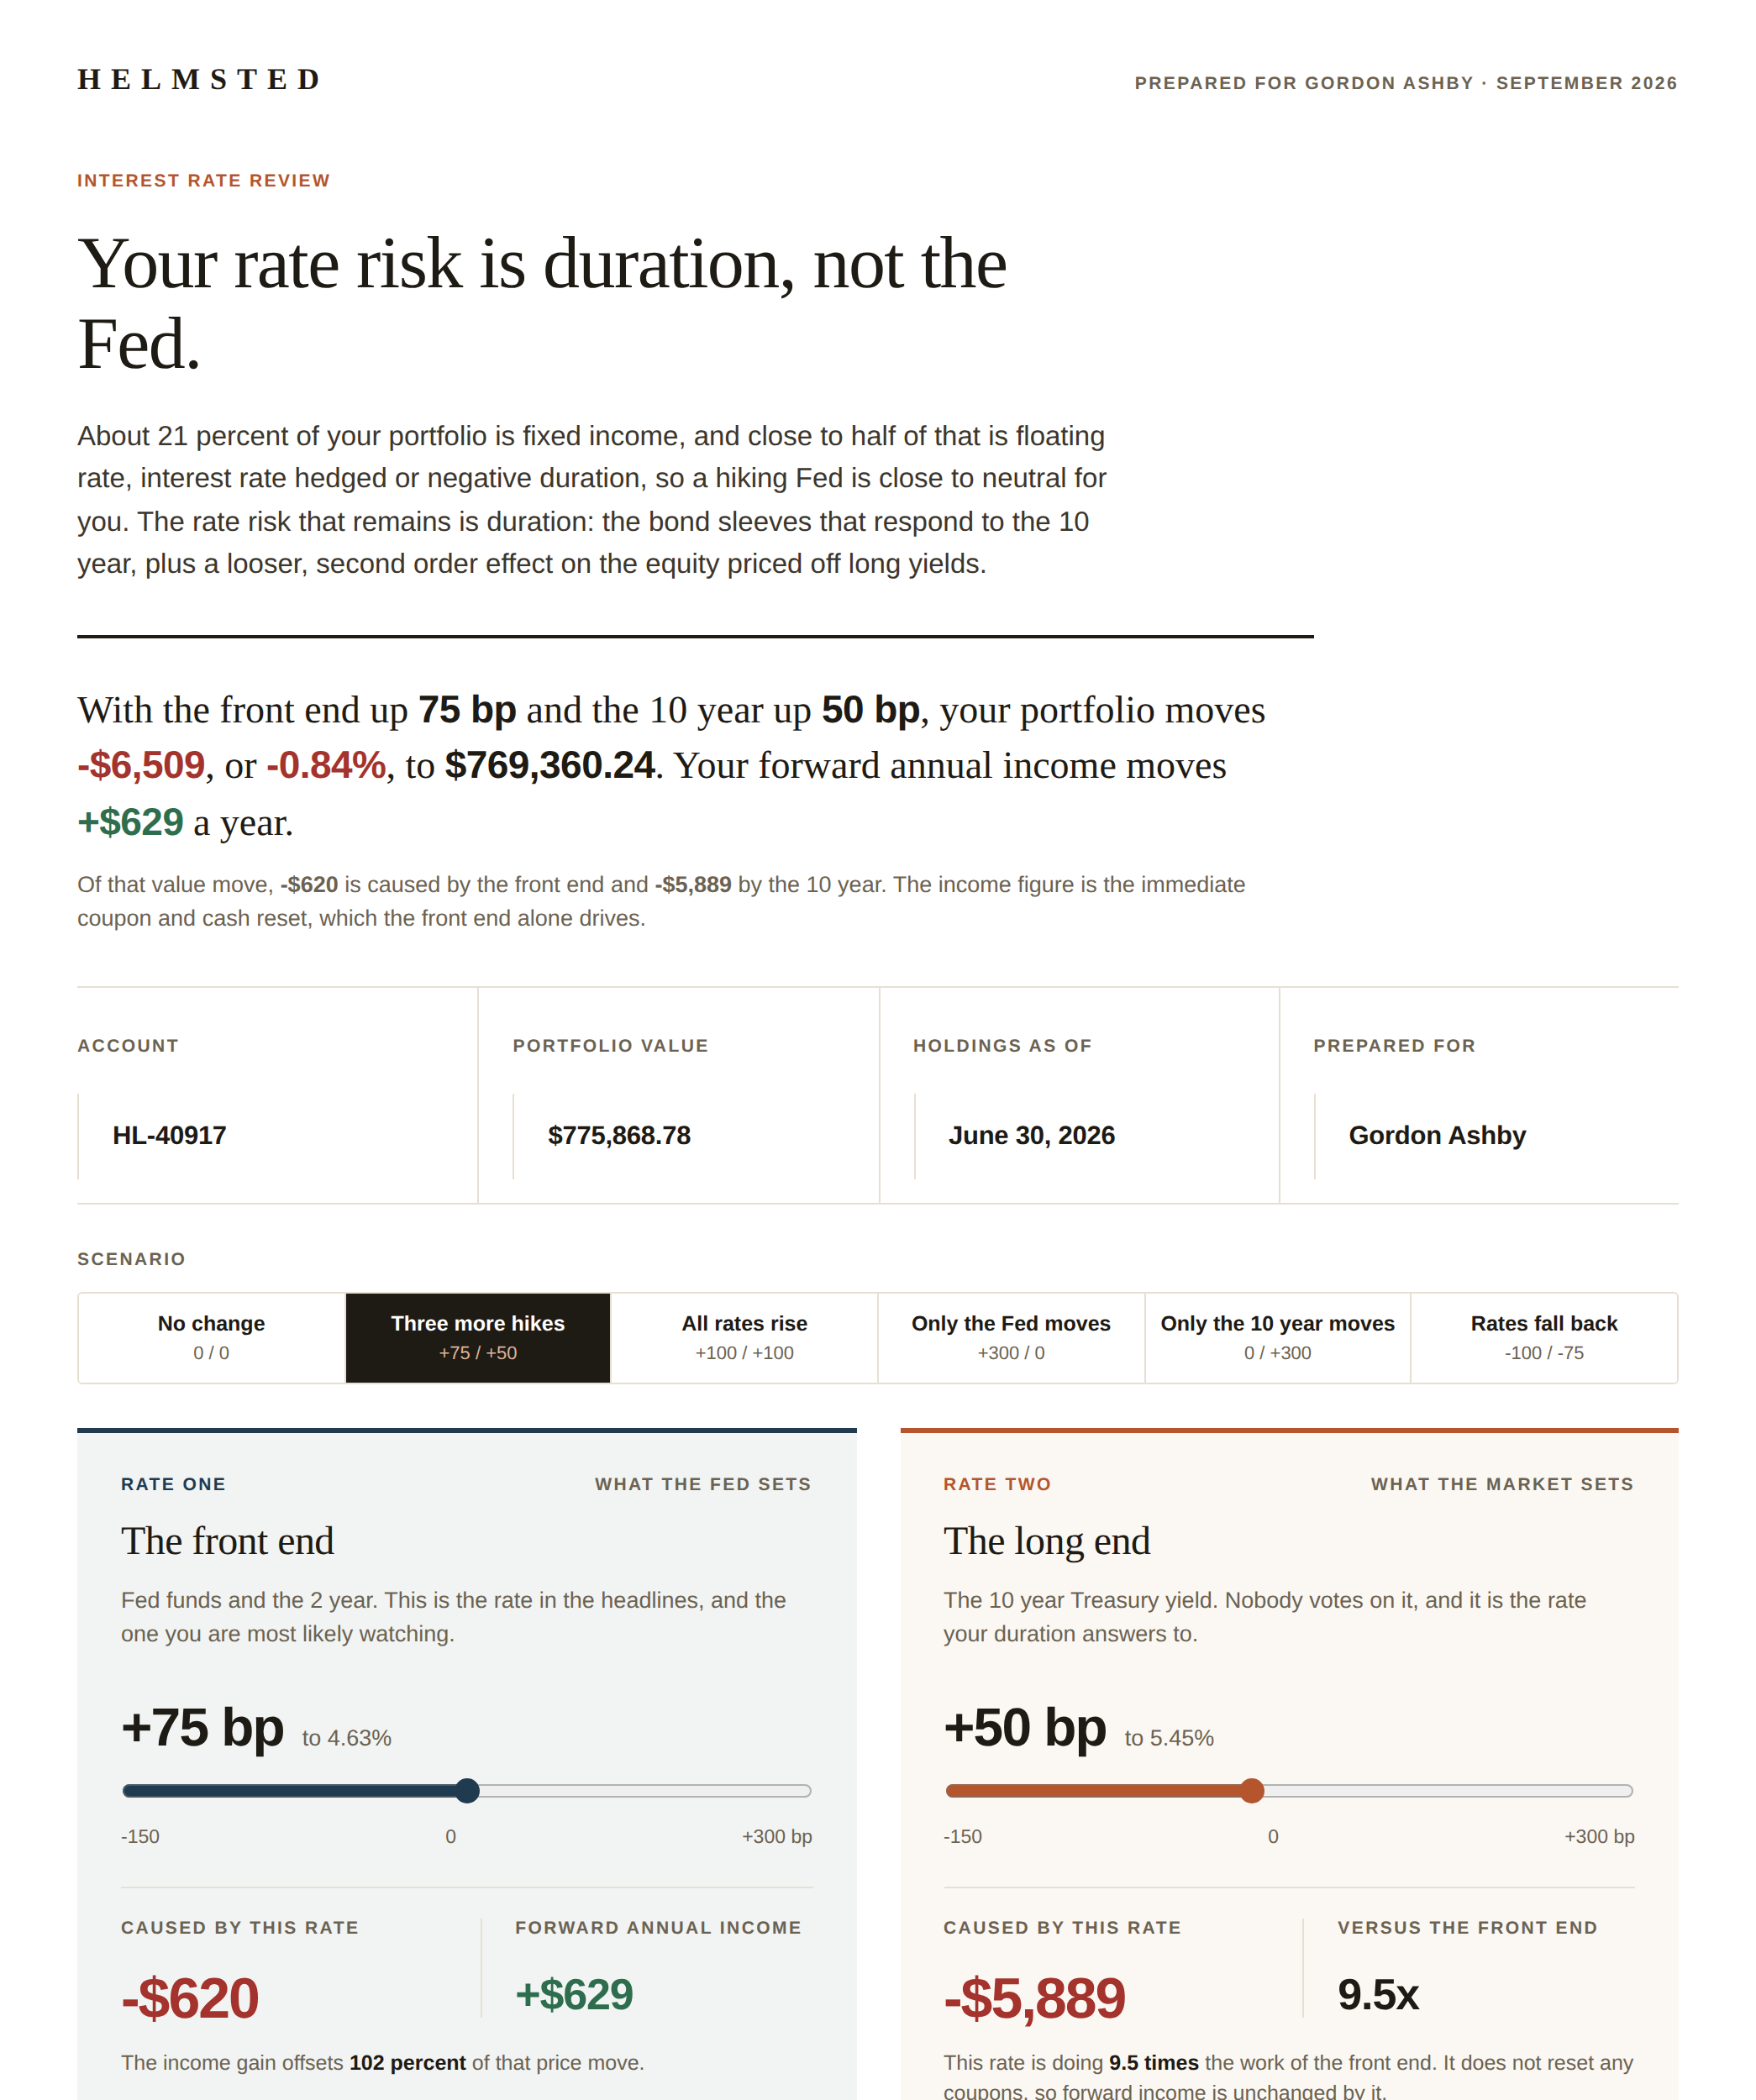
A client asked what the Fed's hike does to his portfolio. Two rate sliders split every holding's effect between the front end and the 10 year: three more hikes cost $620 in price against $629 of new income, while +300 bp on the 10 year costs $35,583, $12,796 of it bond duration alone, with the equity response on a slider.
This week's release: every response ends with a Sources link that highlights the response passage by passage, a Helmsted notetaker replaces native recording on Meet and Teams, and Helmsted now builds Word documents on the firm's letterhead.
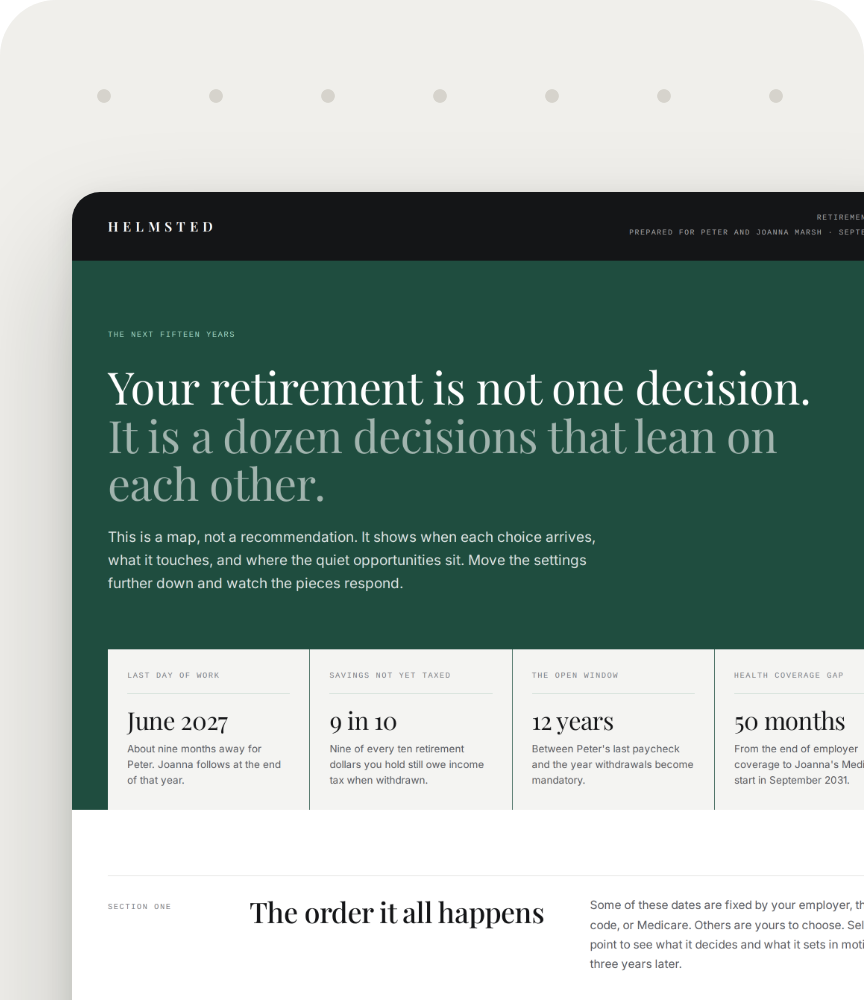
A couple nine months from retirement with a pension election, three stock windows, a Medicare gap, and nine in ten retirement dollars still untaxed. One ask to Helmsted turned it into an interactive map: a timeline of what happens when, live controls for each choice, and four charts that move together.
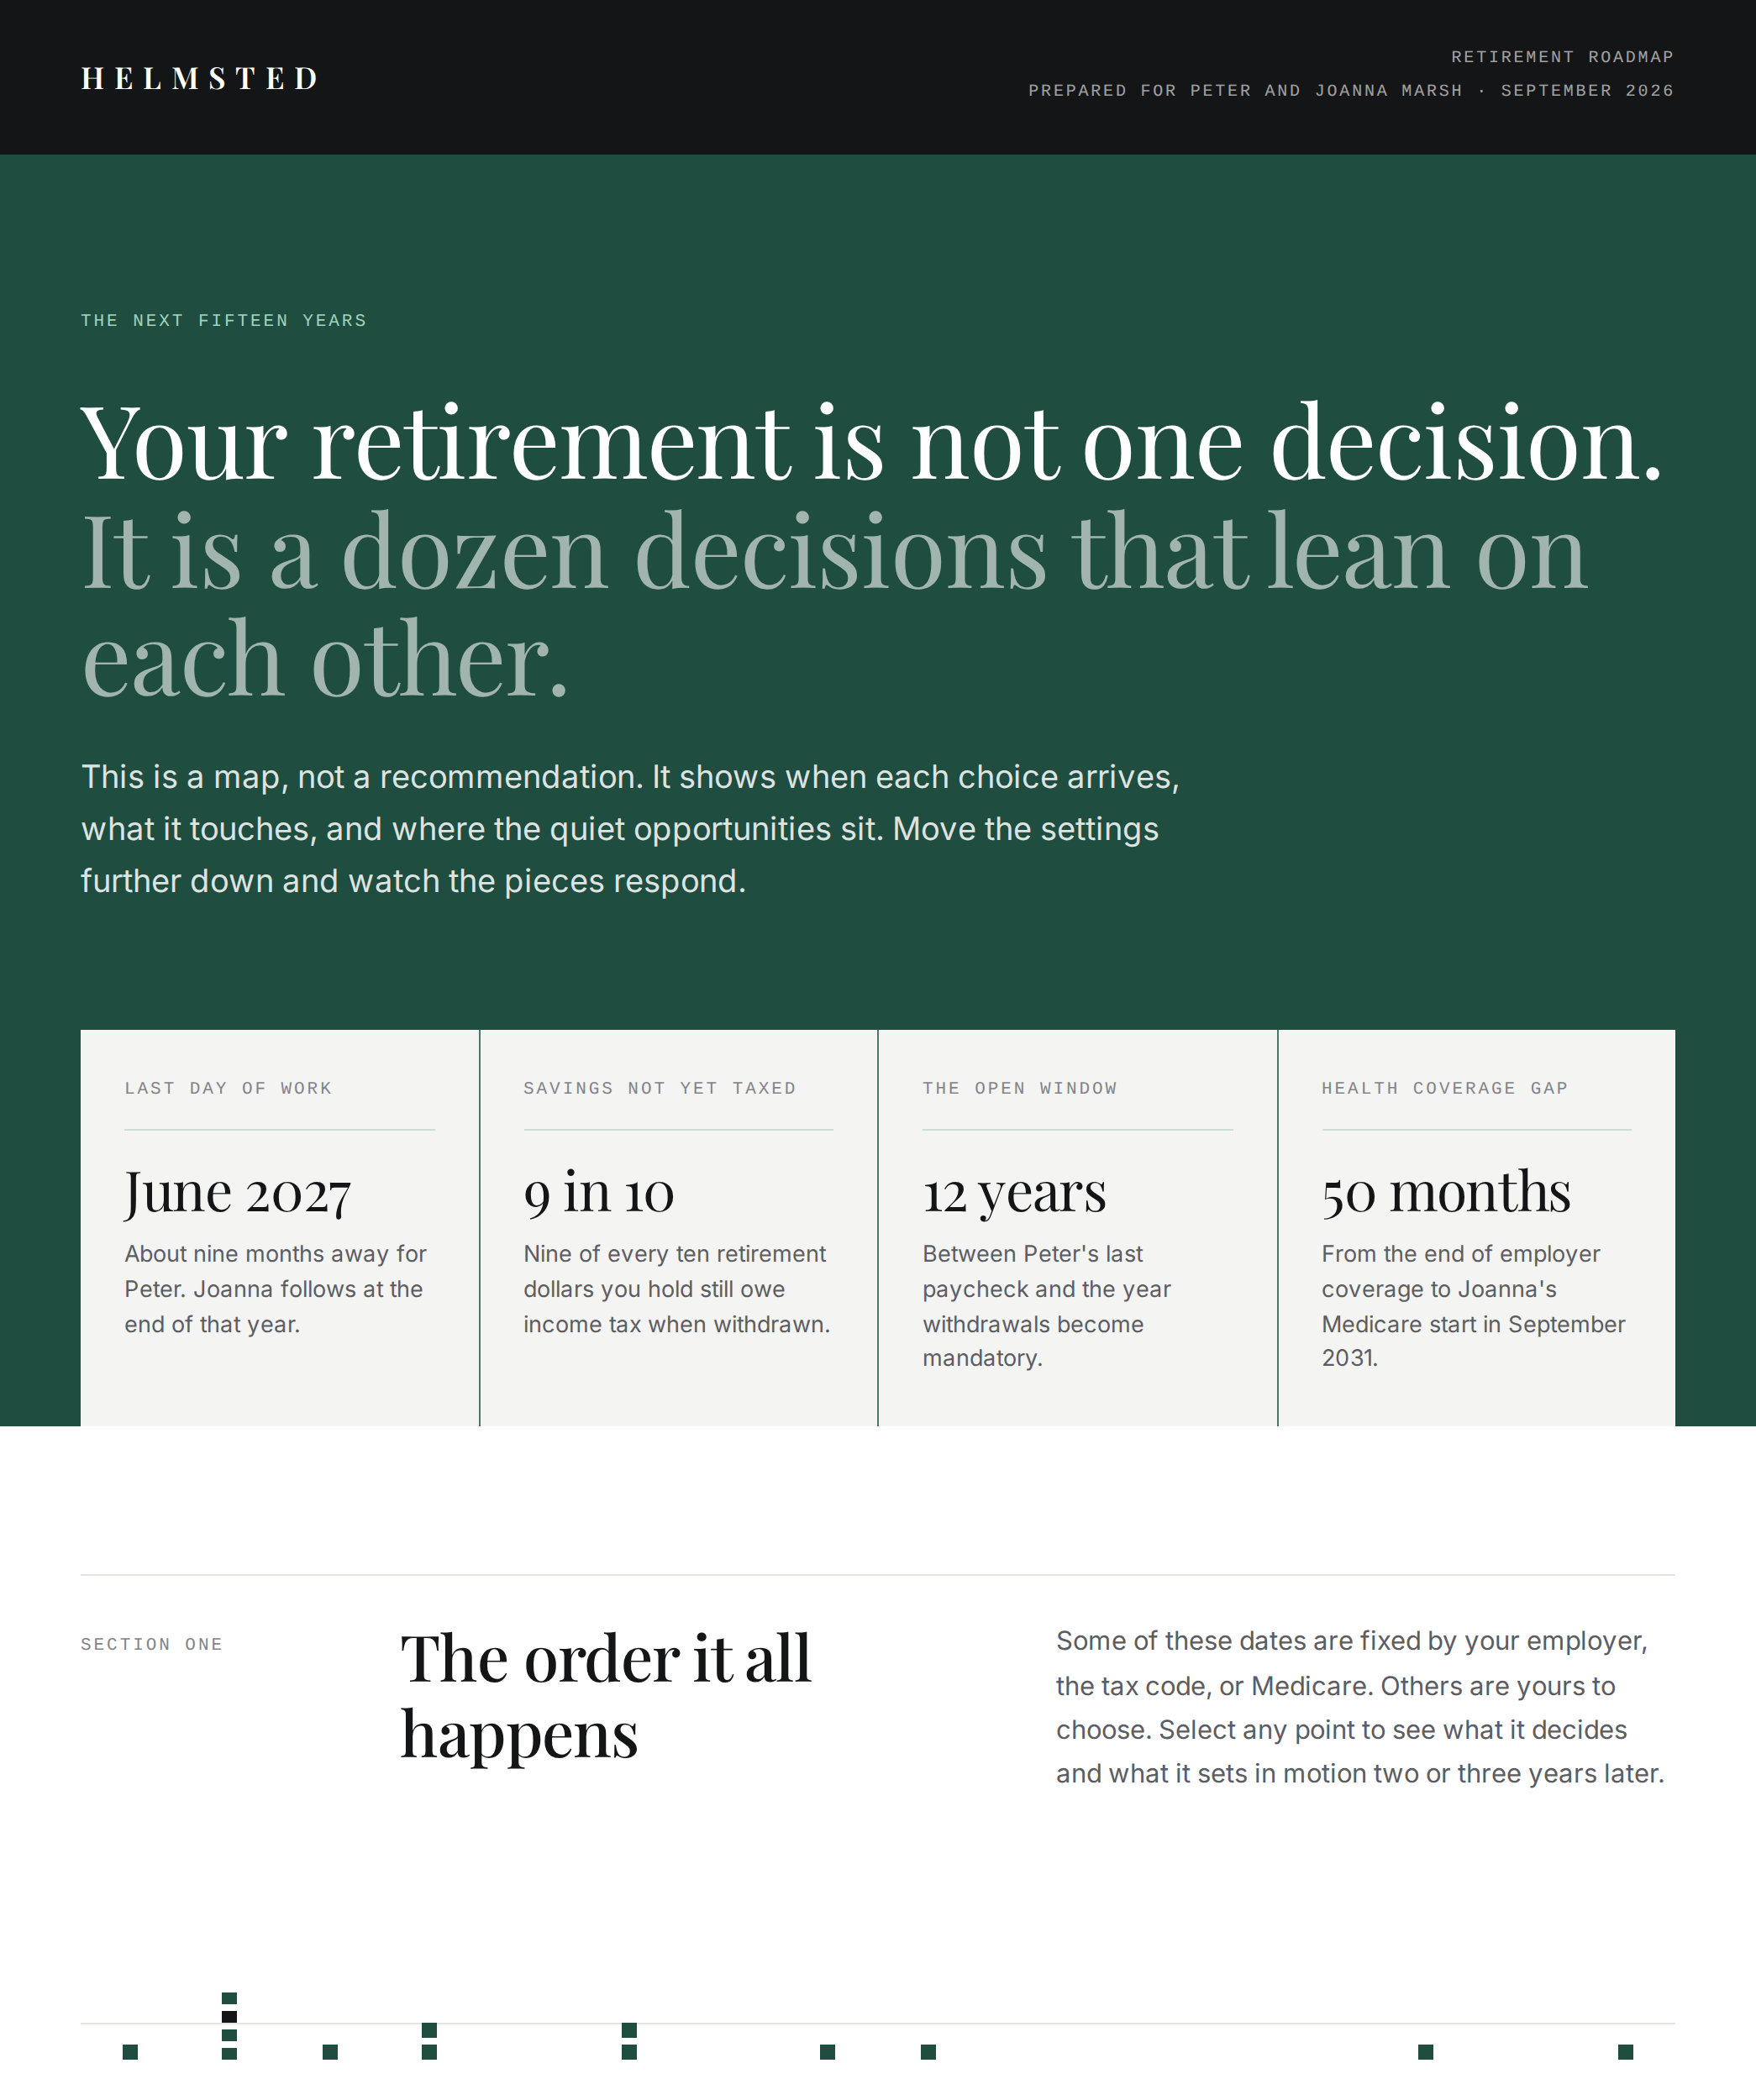
Nine months from retirement with a pension election, three company stock windows, a 50-month health coverage gap, and nine in ten retirement dollars still untaxed: lifetime taxes of $1.79M, $4.89M still tax deferred in 2039, $7.51M to the children, and live controls to change any of it.
This week's release: Google Meet transcripts land on the calendar event and feed the next prep, sessions start on arrival at a meeting, Helmsted manages your calendar from a session, clients book faster from the portal, and sign-in now asks for a passkey or authenticator app.
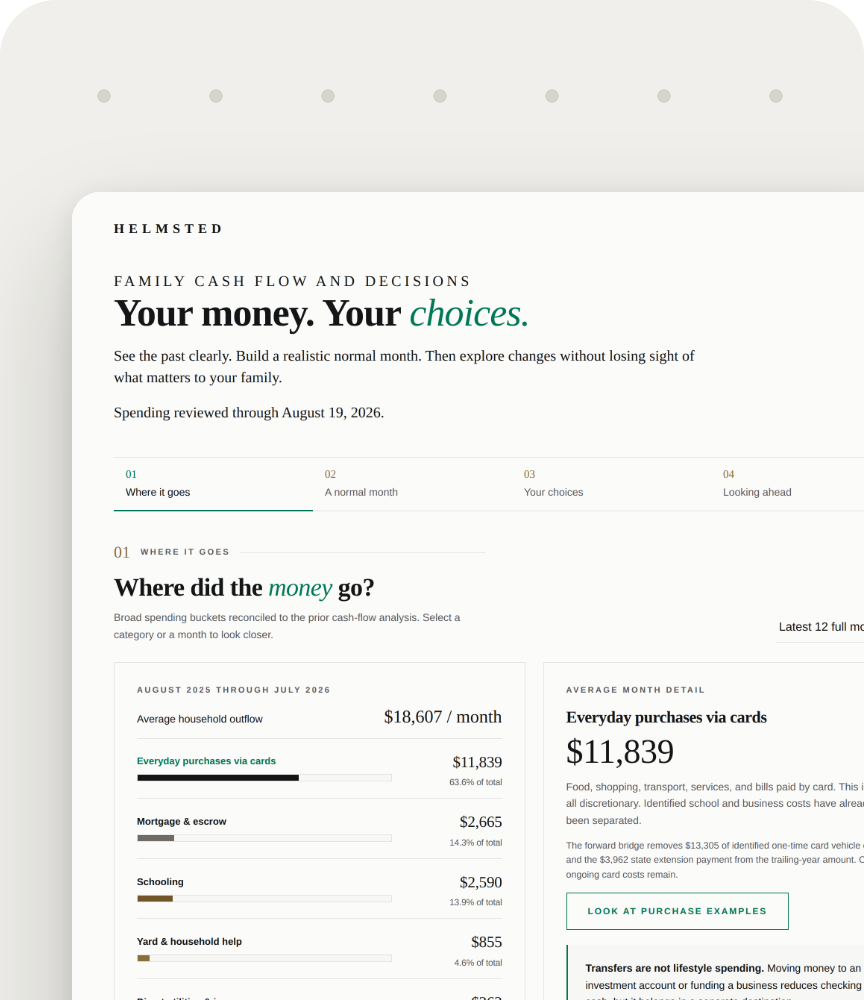
A household with strong income, a rental, and a side business, and a checking account that never matched. One ask to Helmsted turned it into a four-step interactive: where the money goes, a normal month, the choices, and what those choices add up to.
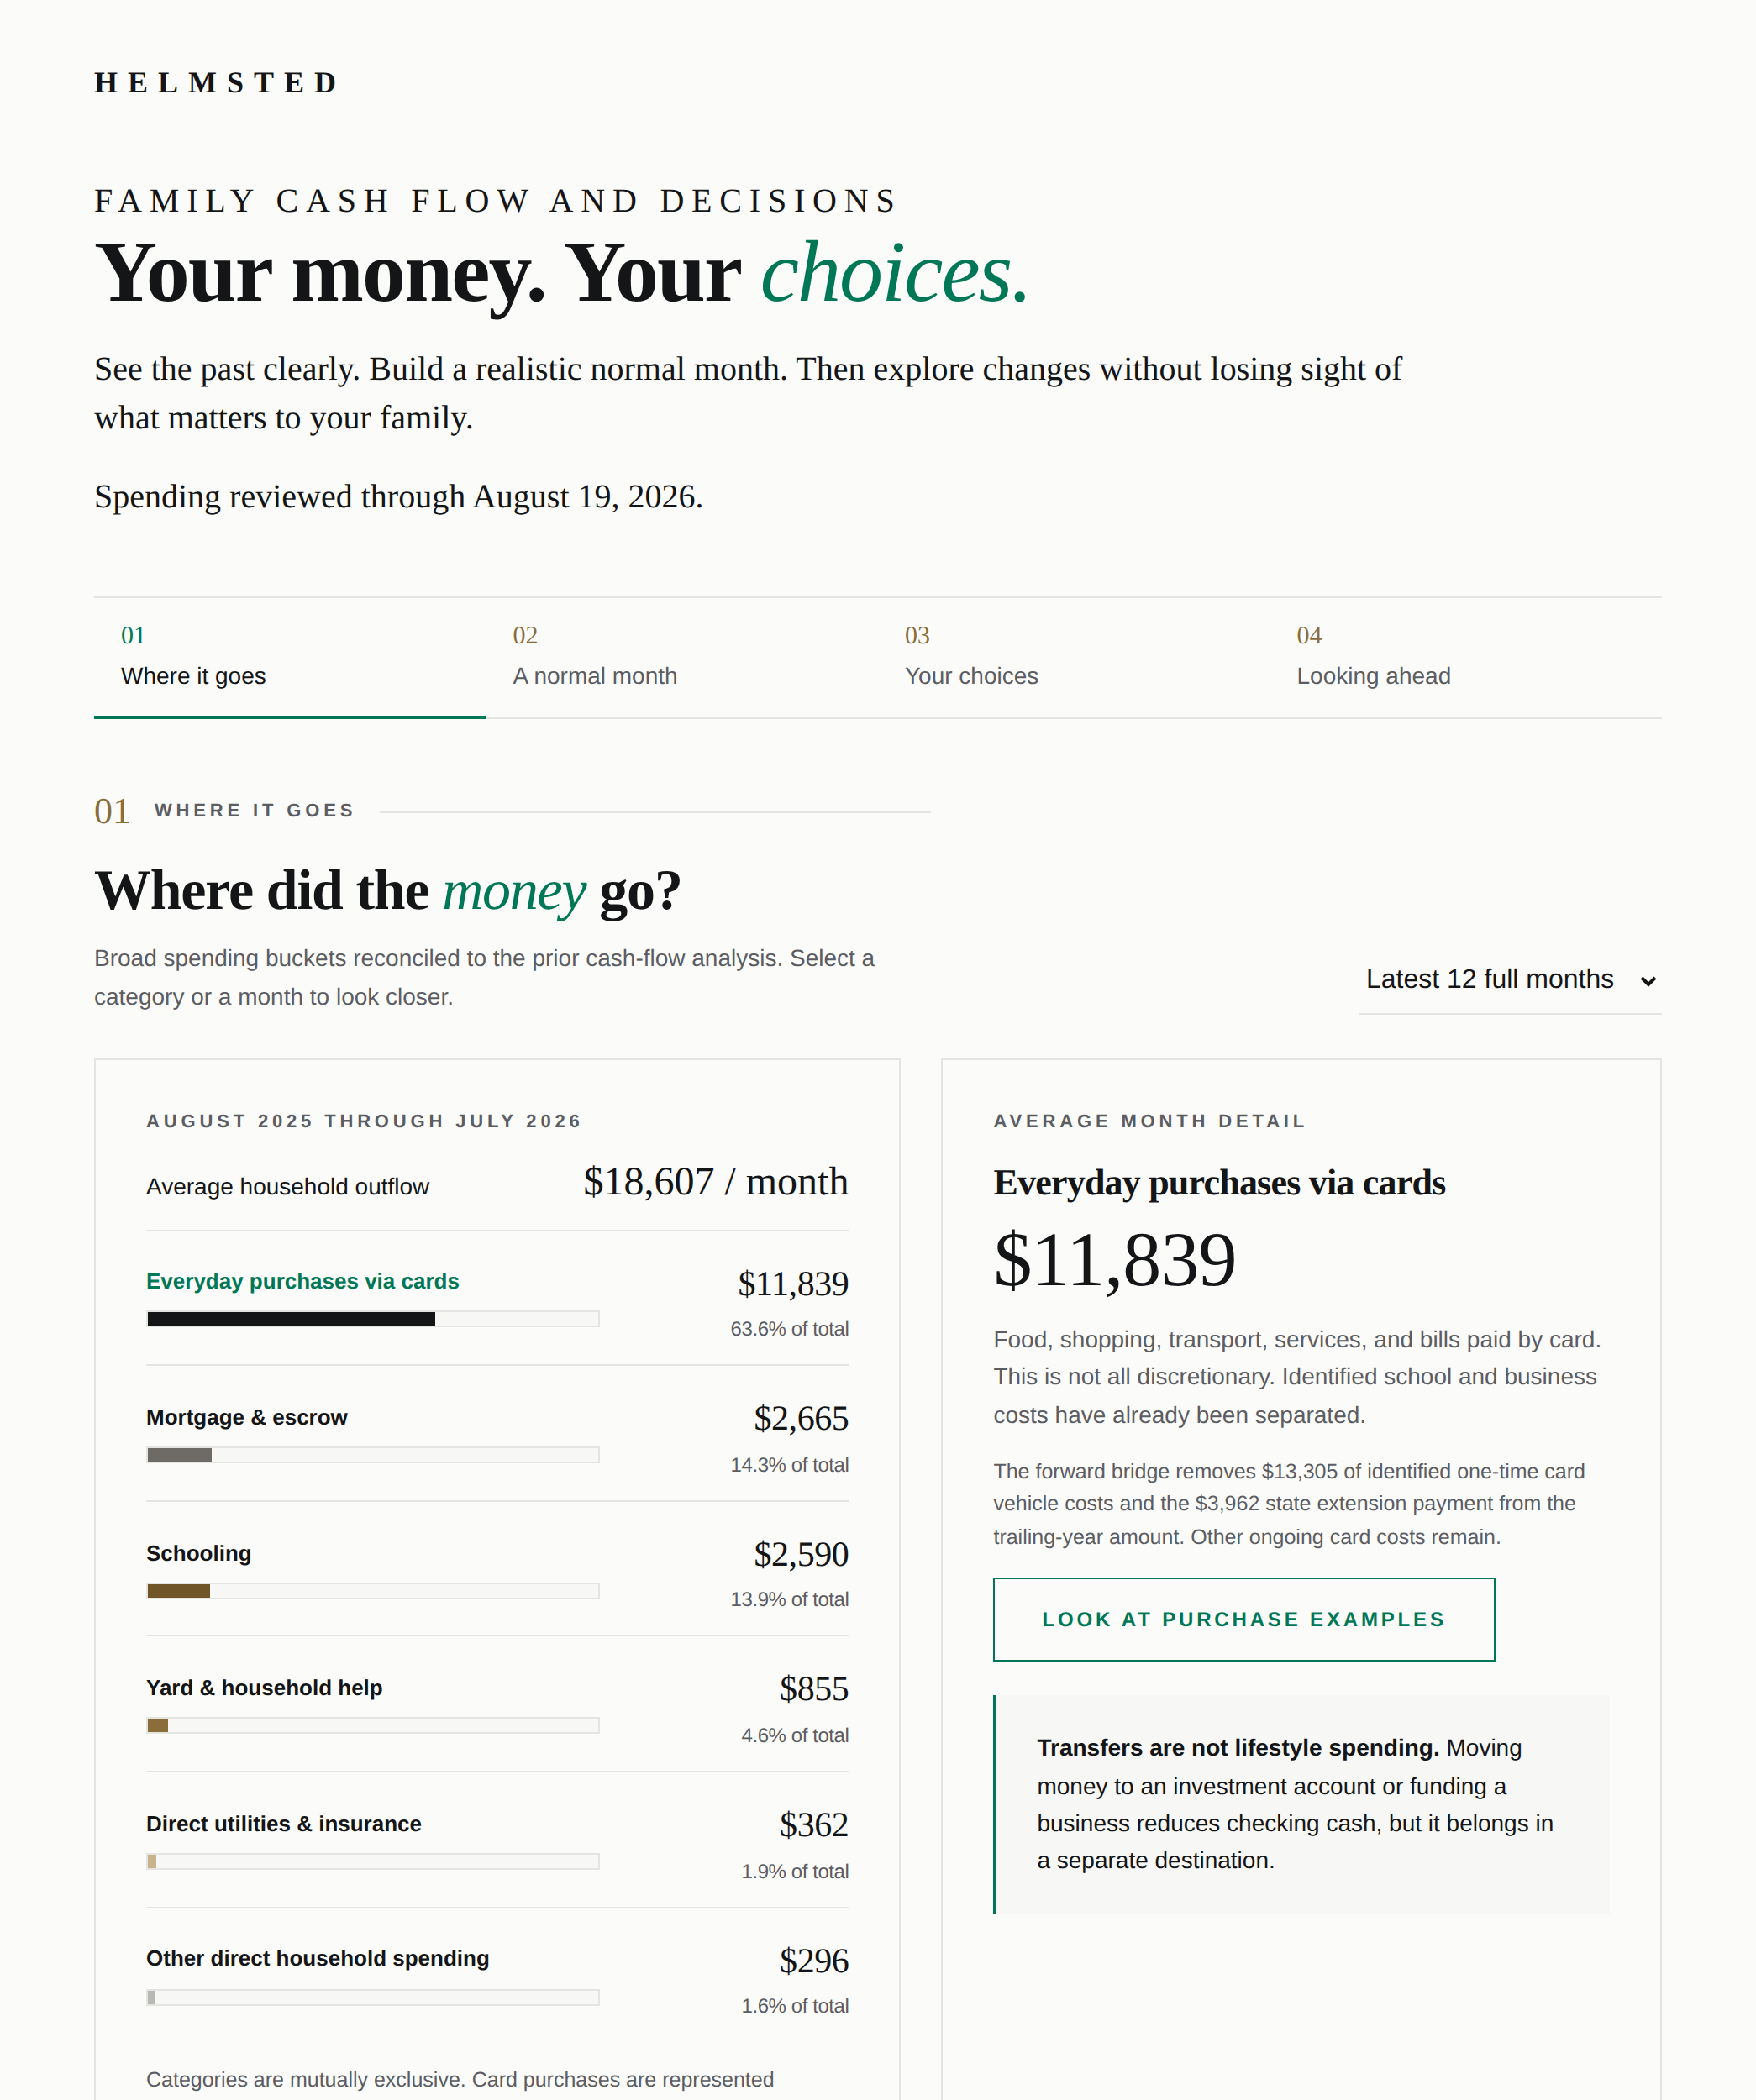
Strong salary, a rental, a side business, and a checking account that always felt tight: history averaging $18,607 a month, a forward need of $16,906, $2,844 unassigned with rental cash and $1,156 short without it, and a larger trim worth $42,976 over five years.
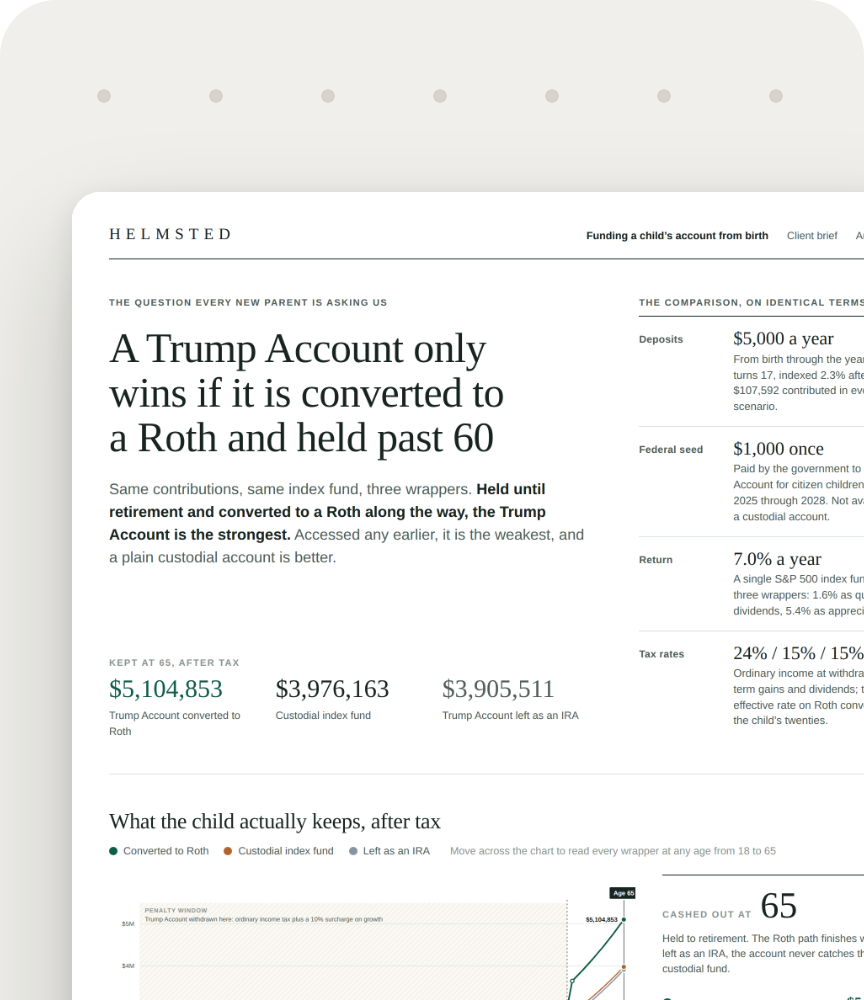
Since contributions opened in July, the same question in every young-parent meeting. The answer is one condition: a Trump Account only wins if it is converted to a Roth and held past 60.
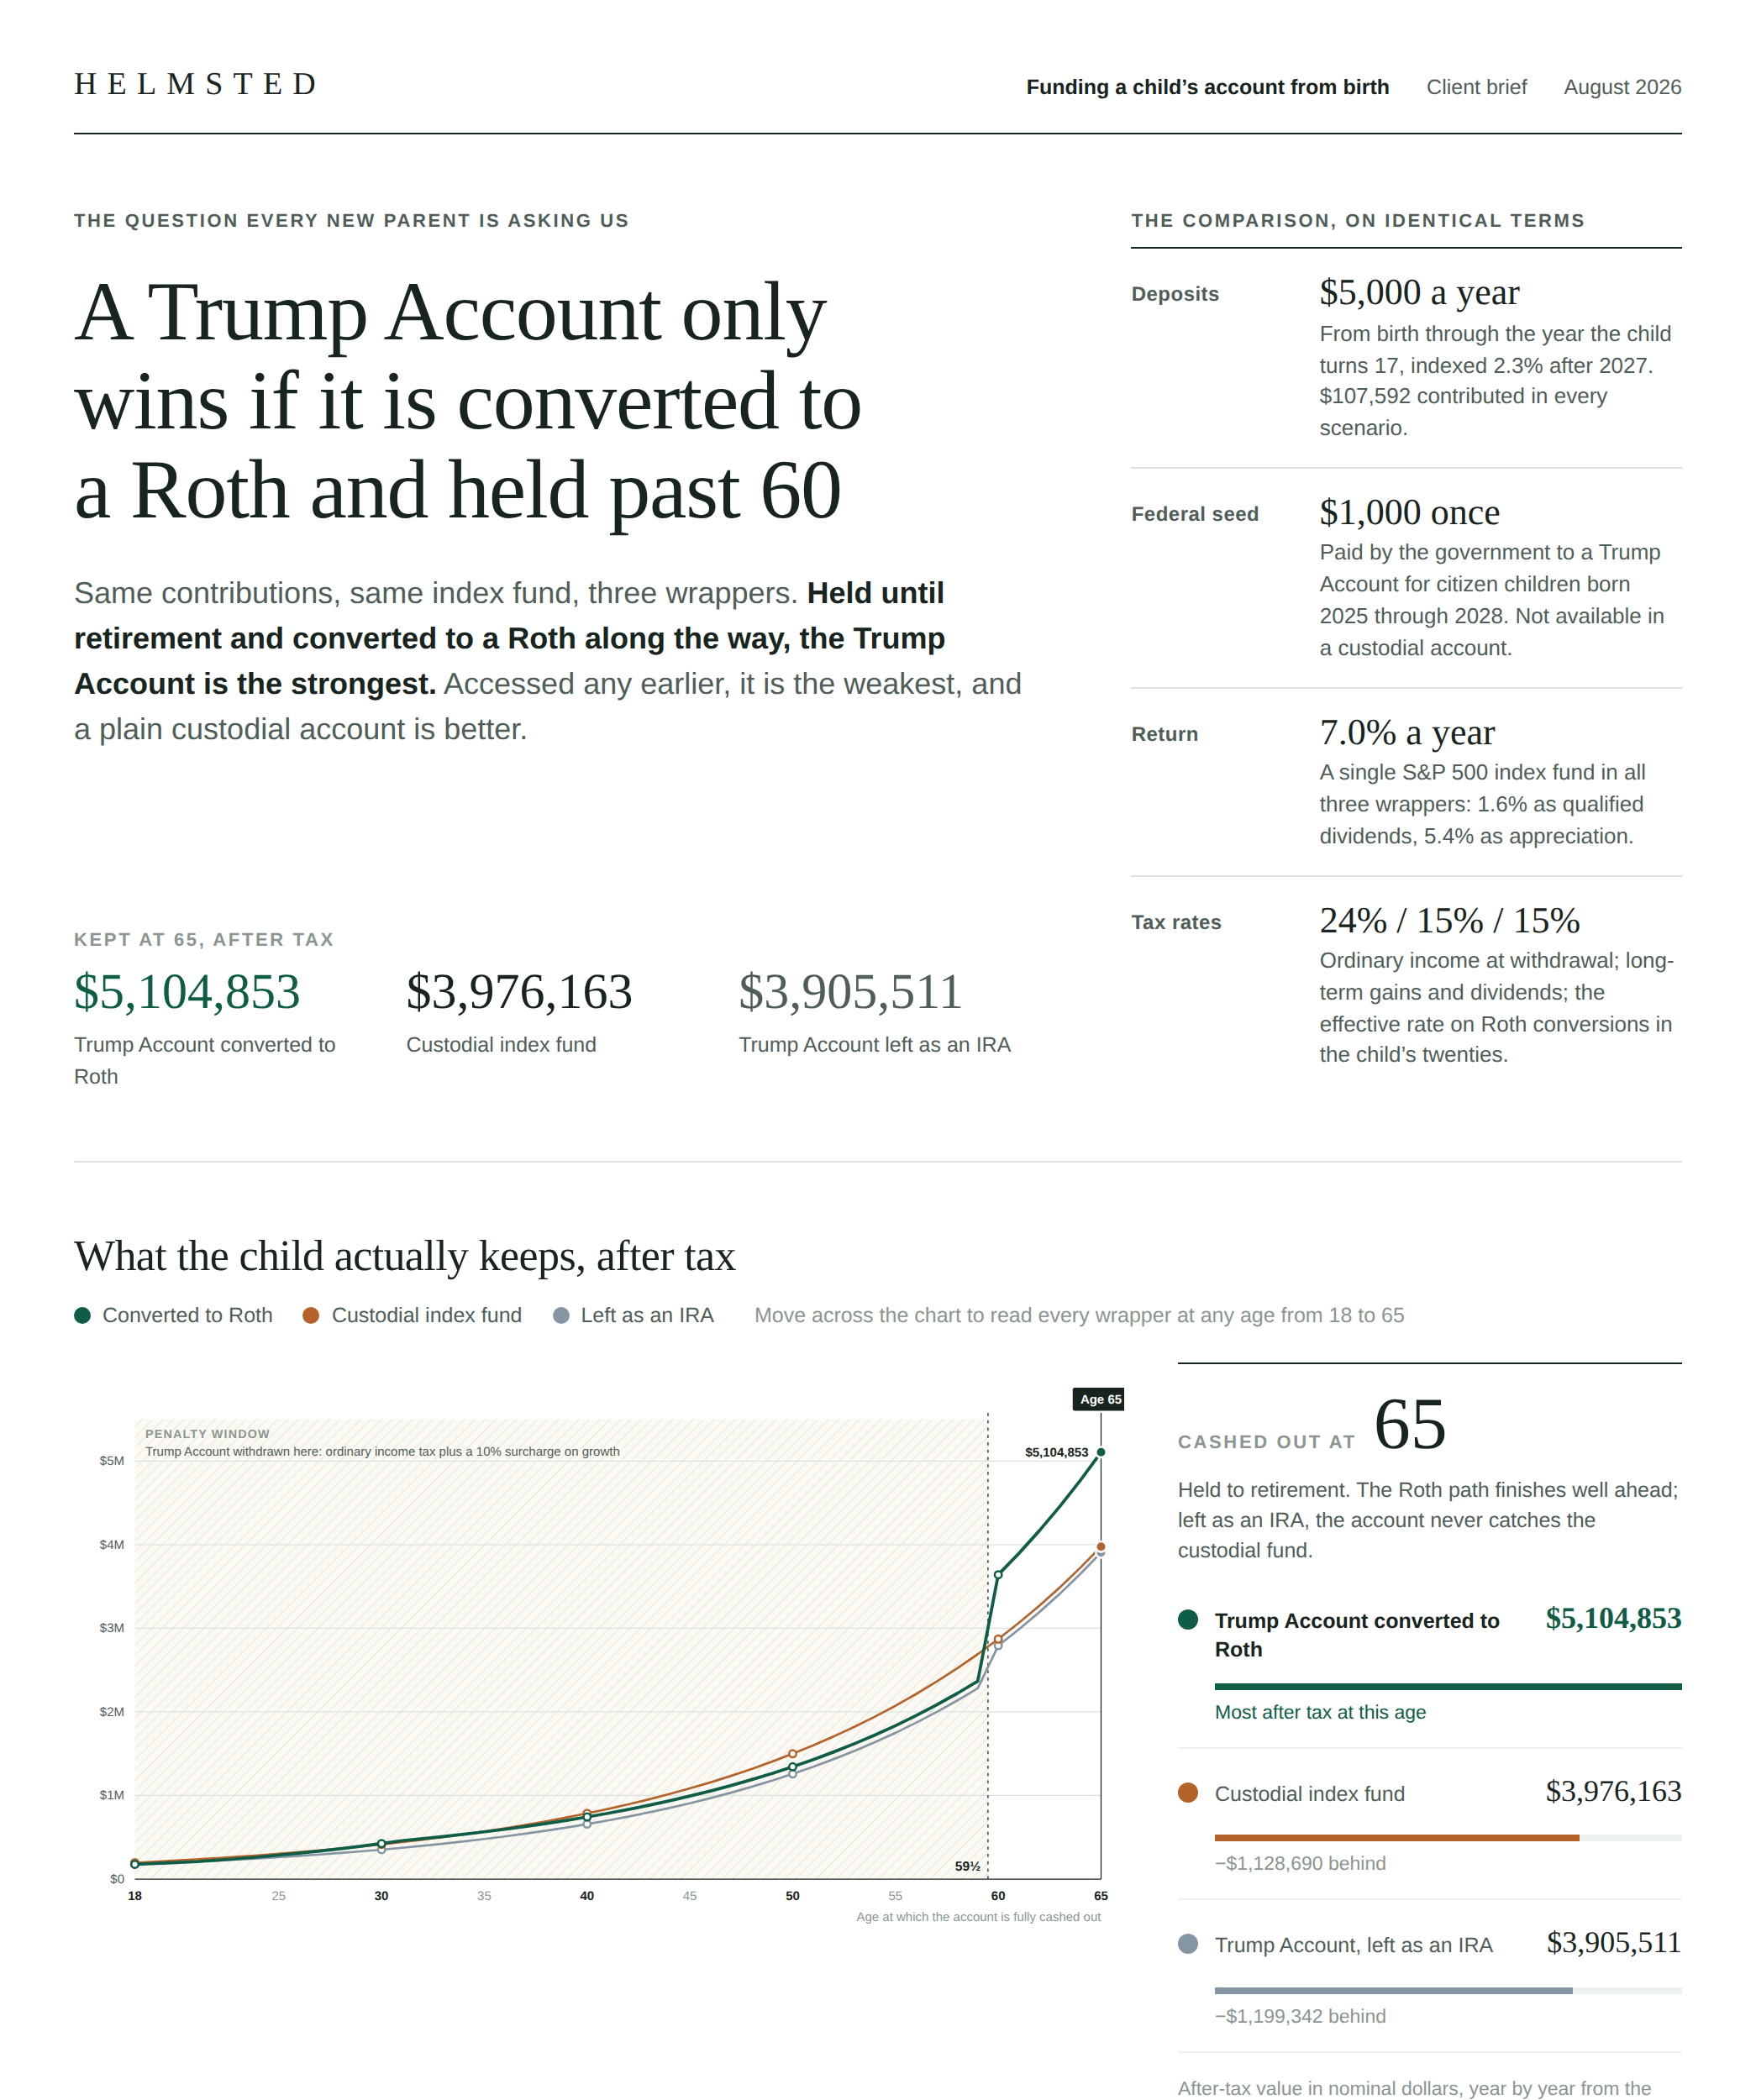
New parents asking whether the Trump Account beats the custodial account they were about to open: three wrappers on identical terms, and the answer that it wins only when it is converted to a Roth in the twenties and held past 60, $5,104,853 against $3,976,163 at 65, and loses at every earlier age.
Helmsted has engaged Vanta for continuous security and compliance monitoring and Sensiba, an independent audit firm, to perform our SOC 2 examination.
A young couple pre-qualified for $1.5 million, a family plan that runs on one income, and a model that opens on the reality instead of the letter.
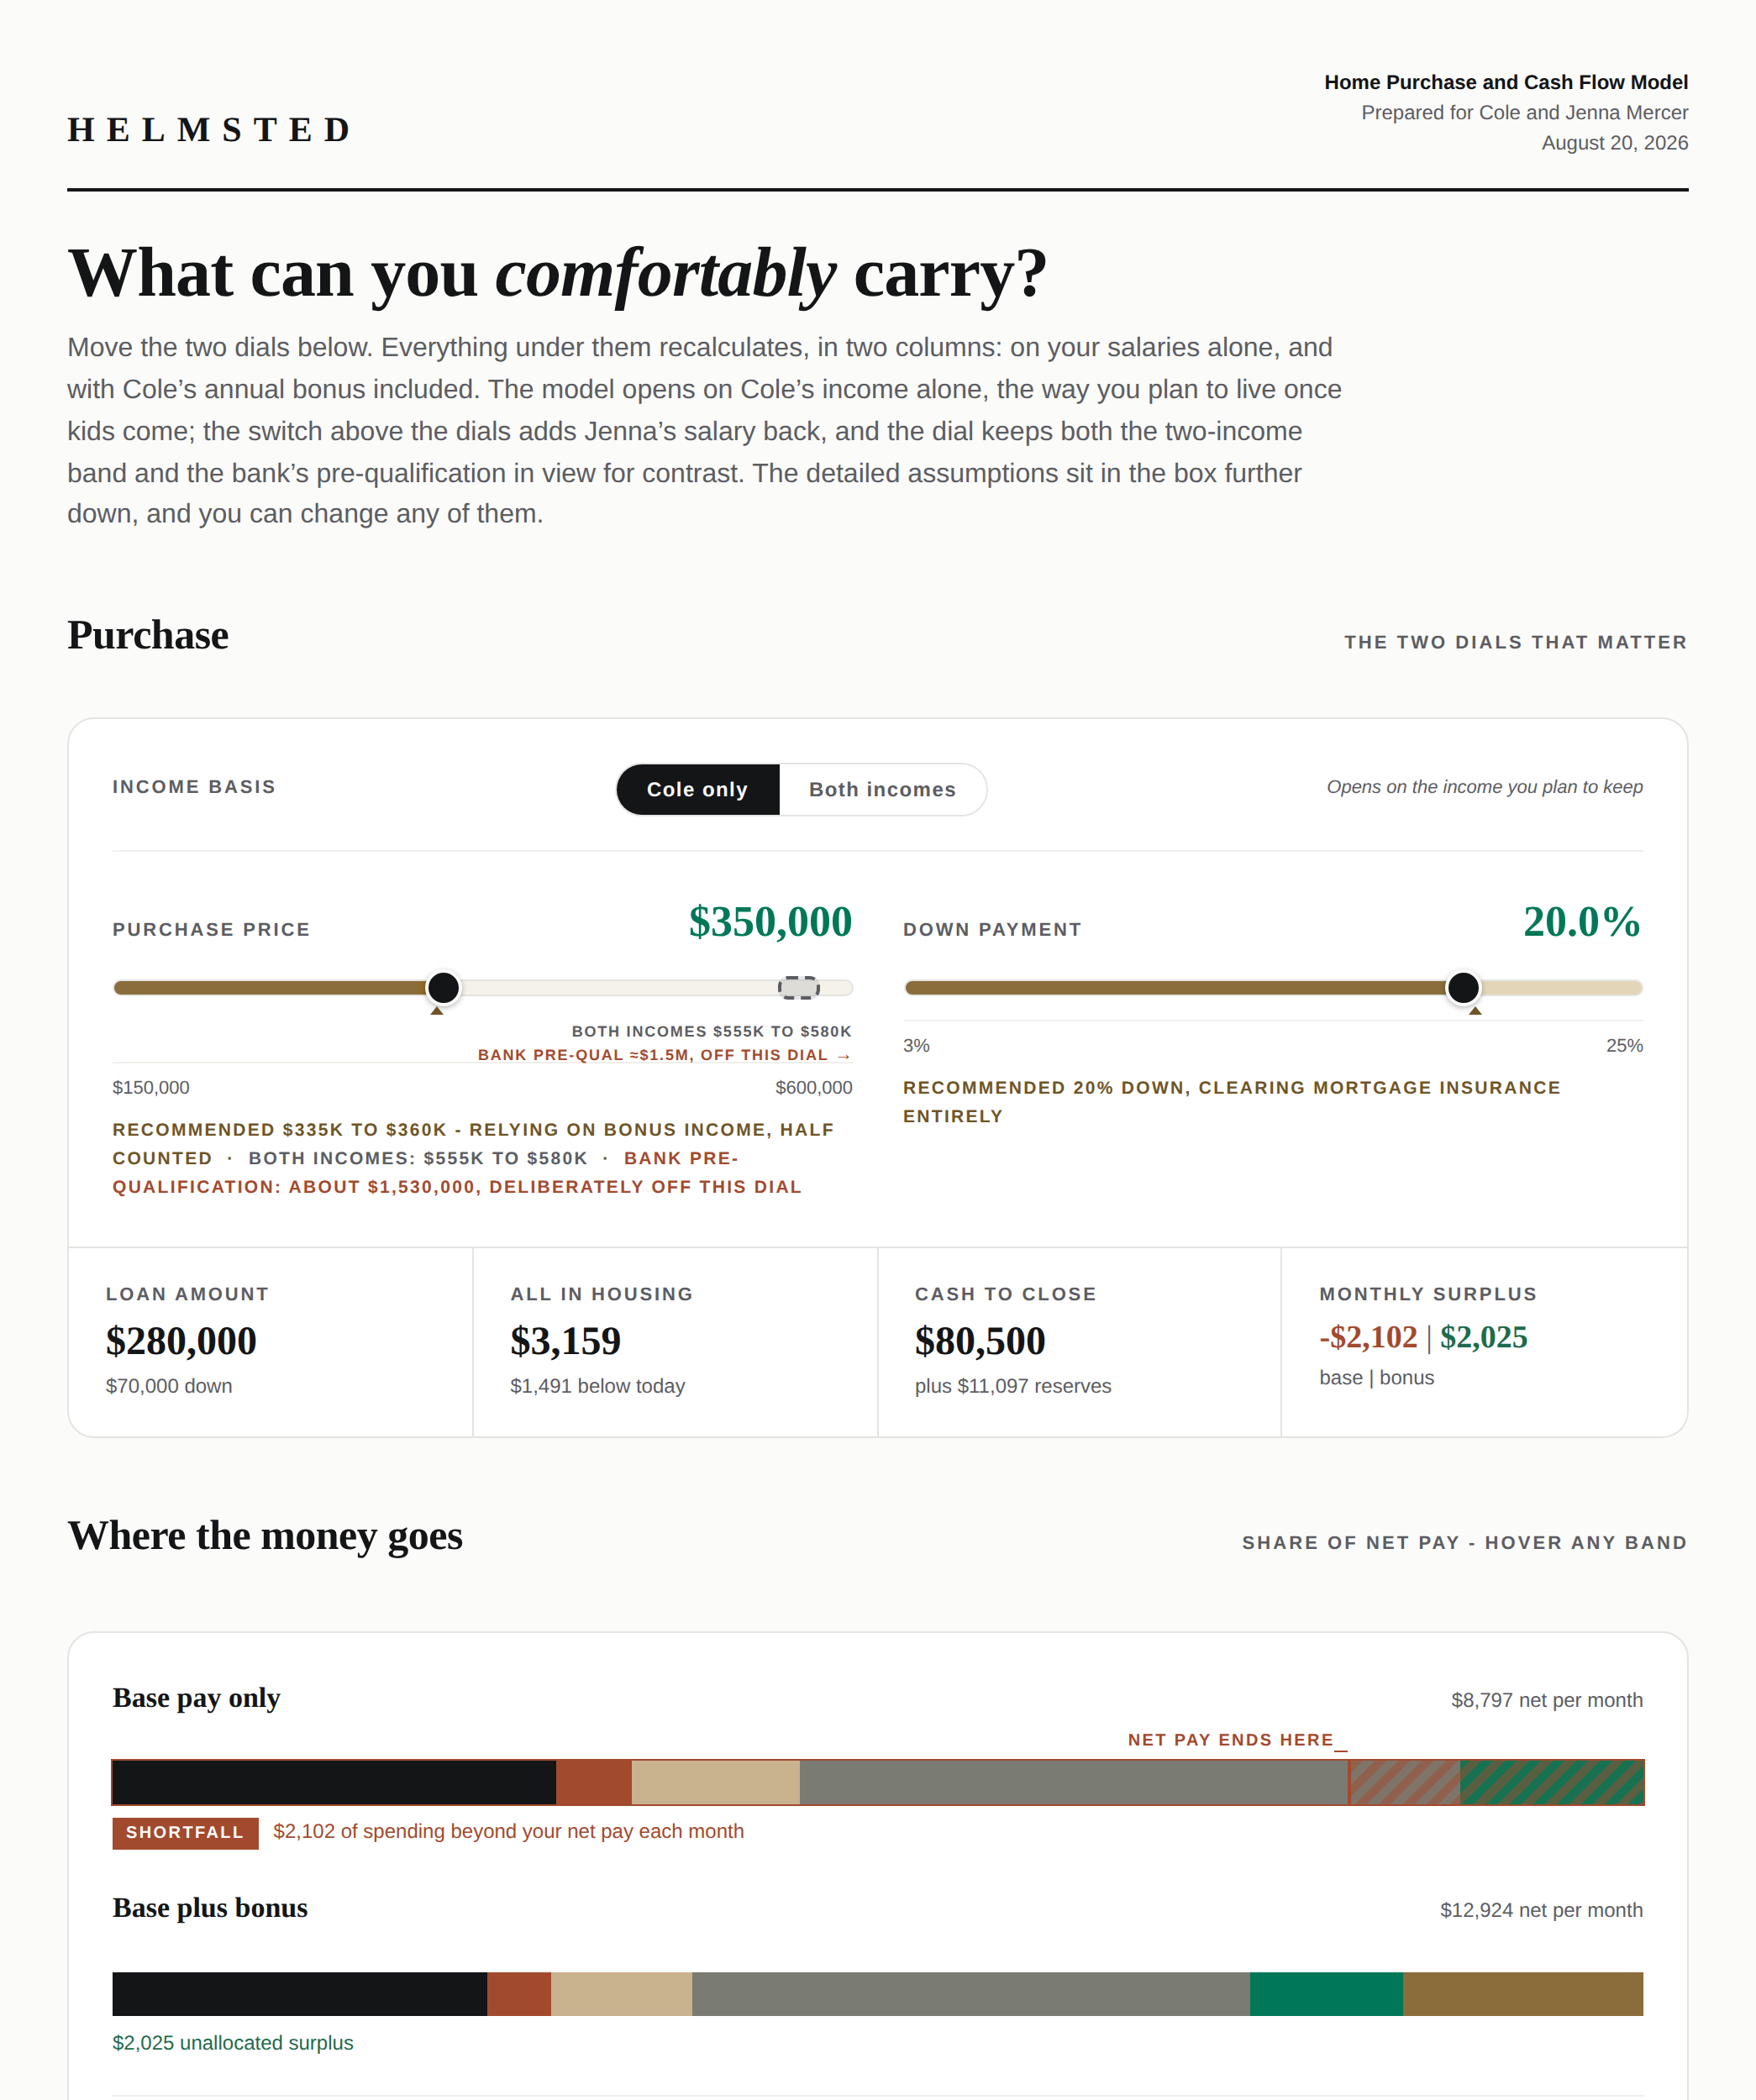
A young couple planning a family, with one income set to pause when kids come: a model that opens on the $335,000 to $360,000 the family plan comfortably carries, keeps the two-income $555,000 to $580,000 as a ghost band, and flags the bank's $1.5 million pre-qualification as deliberately off the dial.

There is a difference between software with AI added on and software built AI-native: one system where the intelligence is the foundation, so planning, communications, and materials all draw from the same living context of the household.

A couple set on claiming Social Security the moment they could, afraid the trust fund would not hold, and a claiming explorer built to start at their answer instead of the advisor's, with the fear modeled as a dial rather than dismissed.

A couple set on claiming at 62 and worried about the trust fund: an explorer that starts at their answer, tests an across-the-board reduction from 2033 against every claiming age, and shows the survivor check the decision leaves behind, $2,765 against $4,898 a month.

Advisors can create and continuously refine interactive, on-brand Social Security planning experiences in plain language: adjust the logic, visuals, and assumptions, then publish to the client portal.

A young couple who saved well but never opened a college fund. College gets covered by earmarking what they already hold, and the 529 does one job: tuition passes through, in and out the same year, capturing the state deduction without ever holding a balance.

A young couple who saved well but never opened a college fund: a twenty-year education bill of $950,000 on one page, college covered by earmarking investments they already held, and a 529 kept purely for state tax savings, roughly $12,000 captured by passing tuition through.
This week's release: files and sessions move between workspaces, portal invite emails are deterministic and editable with a preview link, Helmsted learns across sessions, and materials can now be built as well-formatted PDFs.

Adding a household to Helmsted is as simple as sharing what you already have: drop in files and context, publish an on-brand checklist to the client portal, and let Helmsted walk the client through the rest.

A new client, a stack of operating agreements, and $46,786 back from a tax year that had already ended: a cash balance plan design with a September 15 window.

A 40-year-old eye surgeon, brand new to the firm, whose operating agreements were hiding a retroactive cash balance window: $46,786 of tax back on a closed year, a two-year design worth $91,064, and a CPA-verified timeline to a September 15 deadline.
Drive with search and Ask Helmsted, memory enhancements, per-user audit logs, an account management portal, a richer client portal, and a new workspace UX.

A newly retired couple, a subsidy cliff, legislation still moving, and a new HSA window: the gap years to Medicare on a single report.

A newly retired couple in their early sixties, three years from Medicare, navigating a subsidy cliff, moving legislation, a new HSA window, and a spending rule they agreed to in advance.
Nothing here yet. New issues land on Mondays.
Get the Monday note.
One real advisor workflow every Monday, walked through start to finish, with the sample interaction to go with it. No noise, unsubscribe anytime.